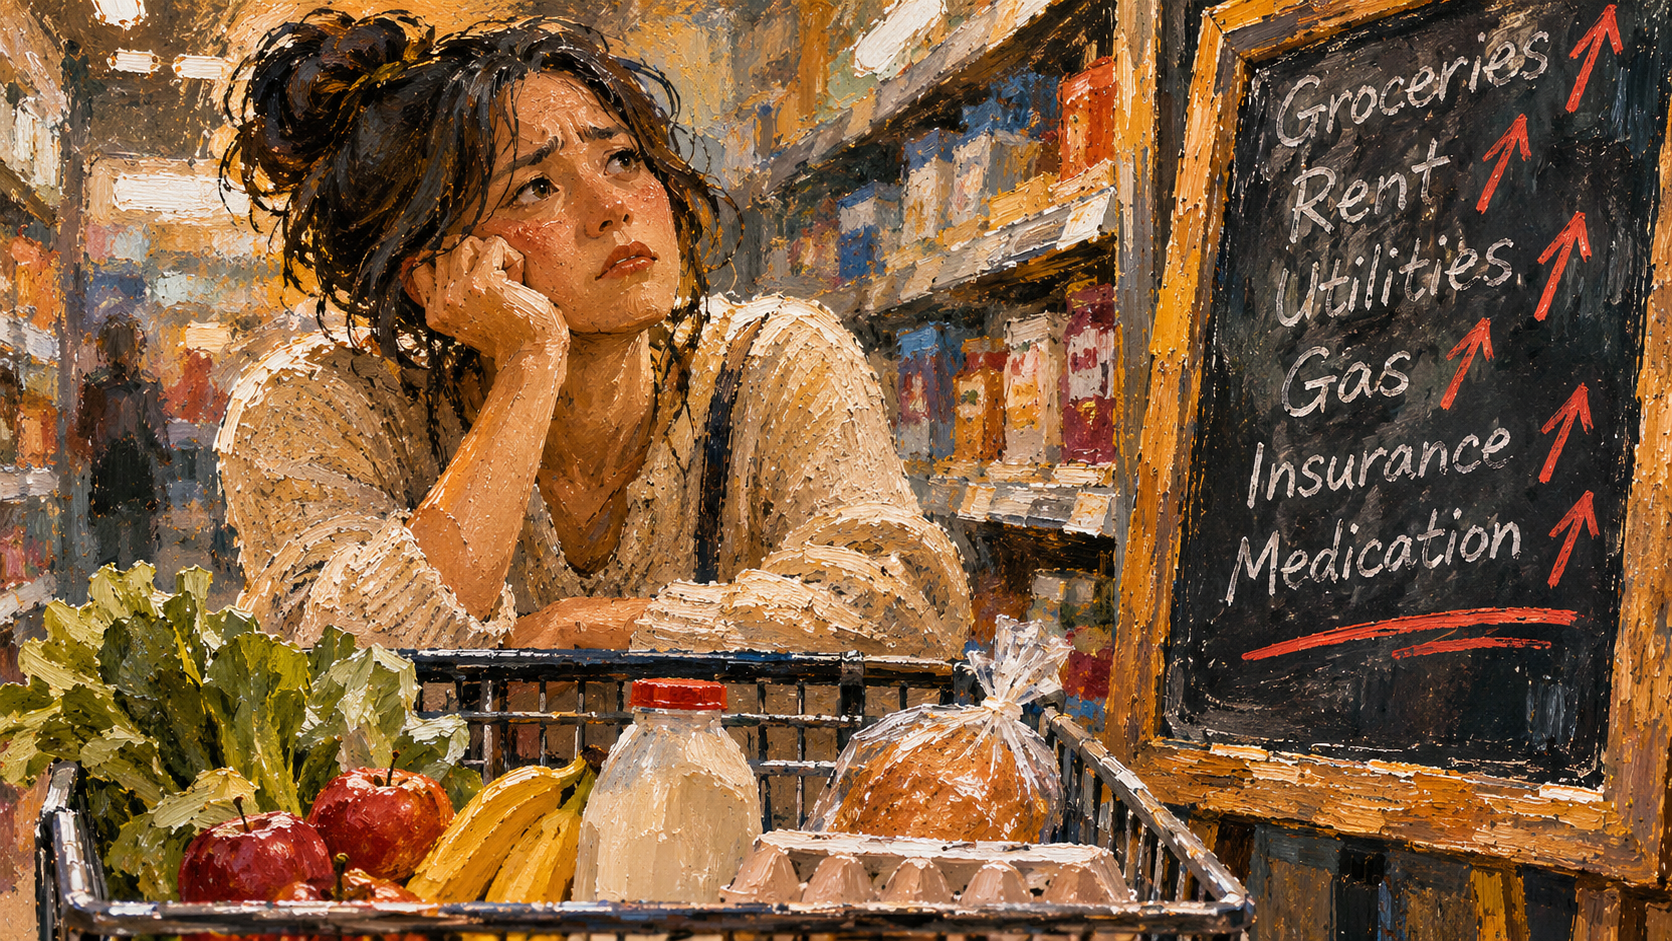
Remember when going to the grocery store with $100 meant coming home with enough food to last a while?
Now you walk out with two bags, a receipt long enough to qualify as a short story, and a sudden urge to check your bank account.
And it is not just groceries.
Rent, electricity, insurance, gas, medication, and practically everything else seem to want a larger share of your paycheck.
Meanwhile, your salary may not have changed much.
People keep telling us to save money, build an emergency fund, and prepare for retirement.
Lovely advice.
But can someone explain how we are supposed to do all that when we are still trying to recover from paying the electricity bill?
When Being Financially Responsible Does Not Feel Like Enough
There was a time when saving money seemed straightforward.
Spend less than you earn. Avoid unnecessary purchases. Set something aside every payday.
Simple enough.
Except today, many people are not necessarily struggling because they are spending recklessly.
They are struggling because ordinary expenses have become harder to manage.
You can skip ordering food, make your own coffee, stop buying clothes, and cancel subscriptions you barely use.
Those things might help.
But they will not magically make your rent cheaper.
And when you are already making sacrifices, hearing someone suggest that you should simply budget better can feel insulting.
Sometimes the problem is not that you are terrible with money.
Sometimes there simply is not much left.
The Mental Exhaustion of Constantly Calculating
Financial pressure does not stop when you close your banking app.
It follows you into the grocery store.
You start comparing prices more carefully. You put something back because you do not really need it. You think twice before accepting a dinner invitation.
You might even feel guilty about buying something small for yourself.
That $7 coffee suddenly becomes a debate about your financial future.
And when you are managing anxiety, the constant uncertainty can make everyday decisions feel even more exhausting.
You start thinking about bills that are not due yet. You calculate expenses before you have received your paycheck. You worry about emergencies that have not happened.
For some people, financial stress affects sleep, concentration, and relationships.
It can become difficult to enjoy the present when you are constantly worried about whether you can afford next month.
That is why saving money is not always just a financial challenge.
Sometimes it is an emotional one, too.
So, Can You Actually Save Money?
Yes, sometimes.
But let us be reasonable about what saving means.
Not everyone can put aside $500 every month. Some people cannot manage $50.
And if your essential expenses already exceed your income, no clever budgeting trick will fix that gap.
You may need additional income, lower fixed expenses, financial assistance, or a combination of those things.
Still, if you have even a little flexibility, there are ways to make saving feel less impossible.
Start With What You Actually Have
Forget the impressive savings goals you see online.
Open your bank account and review what comes in and what goes out.
Start with housing, utilities, groceries, transportation, insurance, and debt payments. Then look at everything else.
The purpose is not to make yourself feel bad about past purchases. It is to understand your actual financial situation.
Sometimes the numbers reveal expenses you can adjust. Sometimes they reveal that you are already doing everything you reasonably can.
Both are useful things to know.
Save What You Can, Not What Someone Else Says You Should
You have probably heard the recommendation to save a certain percentage of your income.
That can be a useful goal, but it does not work equally well for everyone.
If you can comfortably save $5 this week, save $5. If you can save $25 next payday, that is fine too.
A small amount will not solve every financial emergency. But building a habit can help when your circumstances allow it.
And if you genuinely have nothing left after essential expenses, do not put groceries or medication at risk just to meet a savings target.
Surviving the month comes first.
Pay Attention to the Expenses You Barely Notice
Not every financial improvement requires giving up something you love.
Check whether you are paying for subscriptions you no longer use. Review your phone plan. Compare insurance renewal prices. Look at recurring fees that quietly come out of your account every month.
Sometimes the easiest money to save is money you are spending on something you completely forgot you had.
But do not spend six hours trying to save $2. Your time matters, too.
Make Your Grocery Budget Work Harder
You do not need to survive on instant noodles to spend less on food.
Plan a few meals around ingredients you already have. Compare unit prices when shopping. Store brands can sometimes offer similar quality for less.
Freeze leftovers before they become science experiments in the refrigerator.
And do not assume buying in bulk always saves money. It only makes sense when you will actually use what you buy.
The goal is to reduce waste and unnecessary spending without turning every meal into a punishment.
Give Yourself a Small Amount of Breathing Room
This might sound strange in an article about saving money, but hear me out.
If your budget allows it, leave a small amount for something you enjoy.
Maybe it is coffee with a friend, a favorite snack, or an inexpensive afternoon doing something outside the house.
When every single purchase becomes a source of guilt, managing money starts feeling like a punishment.
A budget should help you understand your choices, not make you miserable for having ordinary human needs.
You can be financially responsible and still enjoy something occasionally.
When Saving Money Is Not Possible Right Now
This part matters.
There are people who are working full time, sometimes with additional jobs, and still cannot cover everything comfortably.
They are not necessarily irresponsible. They are dealing with a financial reality where their income is not enough to meet their expenses.
If you are in that position, the immediate priority may not be building savings.
It may be making sure your housing, food, utilities, transportation, and medical needs are covered.
That might mean asking creditors about hardship arrangements, checking eligibility for assistance programs, or looking for ways to improve your income.
And yes, asking for help can be uncomfortable. But struggling silently does not make the bills disappear.
Financial circumstances can change. Being unable to save today does not mean you will never be able to save again.
Stop Comparing Your Bank Account to Someone Else’s Life
One of the easiest ways to feel financially unsuccessful is to compare yourself with people whose circumstances you do not fully understand.
Someone just bought a house. Another friend is traveling internationally. A former colleague bought a new car.
Wonderful.
But you do not know their income, savings, debts, family support, or financial obligations.
You are seeing the purchase, not the entire financial picture.
Social media makes it easy to assume everyone else is doing better.
Meanwhile, you are celebrating because you have paid every bill this month and still have enough money for groceries.
That deserves some recognition, too.
Financial progress does not look identical for everyone.
Your Savings Account Is Not a Measure of Your Worth
Having savings can provide security. That is important.
But having little or no savings does not automatically mean you have failed at adulthood.
Life happens. People lose jobs. Families need support. Medical expenses appear. Cars break down at the worst possible moment.
Sometimes the money you have carefully saved disappears because you need it. That is what savings are for.
And sometimes you have to start again.
It is frustrating, especially when you have worked hard to build something.
But using your savings to get through a difficult period is not the same as wasting them.
Maybe Saving Money Looks Different Right Now
Perhaps this is not the year you build a large emergency fund.
Maybe this is the year you learn where your money goes.
Maybe you reduce one recurring expense, pay down a little debt, or manage to keep $20 untouched until your next payday.
Or maybe you are simply trying to get through the month without borrowing more money.
Those are not all the same financial outcome, but each can represent progress depending on your situation.
Yes, saving money while prices are high can still be possible.
But the amount you can save depends on the money you actually have available, not the savings goals someone posts online.
You do not need to punish yourself for not saving money you never had.
Make a plan that fits your circumstances. Adjust when things change. Ask for help when you need it.
And give yourself permission to enjoy life occasionally.
After all, the purpose of managing money is to make living a little easier. Not to spend your entire life worrying about every dollar.
Grounding thought: A savings goal should reflect your actual life, not someone else’s benchmark. Sometimes progress is saving more. Sometimes it is simply getting through the month without making the situation worse.